Credit Cards
What Card is Right for You?
Learn how to choose an Australian credit card based on your monthly spend, travel habits, annual fees, rewards and benefits you will actually use.
Why do you actually want a credit card?
If you’re only using it to spend money you don’t have, or you don’t plan to use the benefits, why pay for getting a credit card? You could simply use your debit card instead.
And if your main reason is just to split a big purchase into smaller payments, an instalment plan or Buy Now, Pay Later option may make more sense depending on the fees and terms.
A credit card is worth considering when you can pay it off responsibly and actually use the rewards and benefits you’re paying for.
Otherwise, you could end up paying for a card every year but barely using what it gives you.
So before you apply, think about these two things:
1. How much do you spend each month?
First, look at your average monthly spending.
Are you spending $1,000, $3,000, $5,000 or $10,000+ a month?
This matters because the amount you spend can make a big difference to how much value you get from a card.
For example, a card with a $700 annual fee might not make sense if you only spend a small amount each month. But if you put a lot of your regular expenses on the card, the points, travel benefits and other perks may make the fee worthwhile.
Also look at where your money goes: groceries, dining, bills, shopping, travel and everyday purchases. Some cards reward certain types of spending much better than others.
How you spend is the more important factor in choosing the right earn rate and rewards structure.
2. What is your lifestyle?
Before choosing a card, think about how you actually spend and travel.
Do you travel overseas often?
Travel mostly around Australia?
Travel as a couple or family?
Want airport lounge access?
Fly with Qantas, Virgin or book a trip with an online agent?
Do you mainly spend on groceries, dining, shopping and everyday expenses?
There’s no one-size-fits-all credit card. A card that’s great for frequent travellers may be a waste of money if you rarely travel. The best card is the one that fits your lifestyle, spending, and travel habits.
The best credit card isn’t necessarily the one with the most points — it’s the one that fits your spending and lifestyle.
4 Best Cards to Start With…
Not sure which card suits you? Let’s start here!
I have picked the best card for each type of starter, based on your spending and lifestyle while also looking at the earn rate, points value, and annual fee.
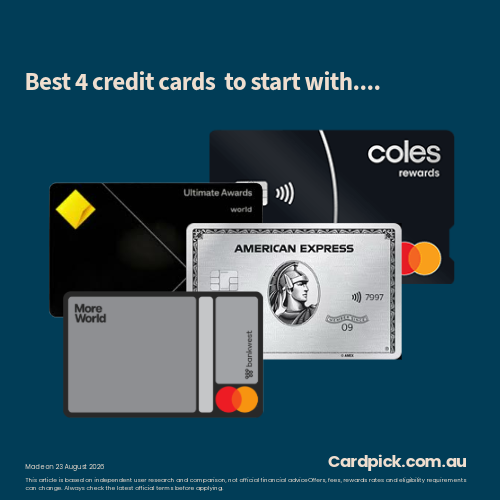
1. Everyday Essential: Coles Rewards Mastercard
Don’t travel + spend under $3,000/month
Best for simple everyday rewards.
For this group, I care more about actual return from everyday spending than travel perks.
Example: Spending $3,000/month, points earning rate for this card is 2 pts : 1$ = 72,000 pts per year and Flybuy has Pay with Point Option 2,000 points = $10 at Coles, Bunnings, Liquorland
**It means you earn reward $360 per year with $99 annual card fees = your earn reward $261 per year at least. **
Why I picked it: Low fee, simple rewards, and good value for someone who doesn’t travel but if you would not mind $200 benefit. Stay with debit card <some debit card is earning pts soon!> or look for instalment plan card with no fees instead. But if the card has fees, I would better recommend Coles card.
The downside: you’re mainly using the Flybuys ecosystem. If you don’t shop at Coles or don’t like Flybuys, there is no point for you to get this card.
2. Travel Explorer: Bankwest More World.
Travel + spend under $3,000/month
Best value for travellers
This is where Bankwest really makes sense.
You travel, but don’t spend enough to justify a super premium card.
Here is what you can get from Bankwest.
- 10 lounge visits
- 0% international transaction fee
- Complimentary overseas travel insurance
- $270 annual fee
- More Rewards points with cashback/gift card options
Example: $2,500/month
$30,000/year → 75,000 points/year using the current published earn rate.
And you also get 10 lounge visits + 0% international transaction fee! Not many cards can provide this at $270 annual fees.
Why I picked it: You get the travel benefits you actually need without paying for a $700+ premium card. The cheapest Lounge pass we could find is about $35, just lounge access is already covered by your fees!
3. Reward Maximiser: CommBank Ultimate
Don’t travel + spend $4,000+/month
Best for big everyday spenders
If you don’t travel, I don’t want you paying extra for travel benefits you won’t use.
CommBank Ultimate is interesting because the monthly fee is waived when you spend $4,000+ in the statement period.
Example: $4,000/month
$48,000/year → ~96,000 points at 2 points : $1.
Based on the redemption value you’ve personally seen :** 100,000 points ≈ $350–$450**
So approximately:** 96,000 points ≈ $336–$432** reward value with $0 annual fee per year.
Why I picked it: Strong everyday earning + no fee when you hit the $4k monthly spend.
Important: CommBank is moving from Awards to Yello from 1 October 2026. We will post the update soon. There is not much change on the CommBank card.
4. Smart Traveller: Bankwest More World < Yes! Still Bankwest >
Travel + spend $4,000+/month
Best overall travel value!
Yes, the same card wins Type 2 and Type 4. Because…
Why pay more just because you spend more if the card already gives you the travel benefits you want?
- 10 lounge visits
- 0% international transaction fee
- Travel insurance
- $270 annual fee
- Rewards on everyday spending
That seems more than enough for a single or couple traveller. If I’m spending at least $4K a month, I’d still choose Bankwest.
BUT…
What if you spend at least $4K every month and travel as a couple or family? What’s the best card for you?
5. Best for Family Travel — Amex Platinum
The biggest advantage of Amex Platinum over other cards is that some key travel benefits aren’t tied to the Primary Cardholder being present unlike many card.
**Travel insurance + eligible lounge access can still be used by eligible Additional Card Members when they travel without the **Primary Cardholder.
For lounge access for Additional card holder, this includes:
- Centurion Lounges — Australia, USA, Hong Kong, London, Tokyo & more
- Escape Lounges — mainly across the USA
- Other Amex partner lounges — available at selected airports worldwide
But there is an important downside from 1 October 2026:
⚠️** Priority Pass changes**
Priority Pass is one of the biggest lounge networks worldwide, with particularly useful coverage across Asia, including popular destinations such as Singapore, Japan, Hong Kong, Malaysia, and Thailand.
Before 1 October 2026: one nominated Additional Platinum Card Member could also have complimentary Priority Pass membership.
From 1 October 2026: Priority Pass becomes Primary Cardholder only. Additional Card Members will no longer receive complimentary Priority Pass membership or lounge access. (American Express)
However, Amex Platinum can still be attractive for families because the card has other lounge networks and travel benefits that are not simply tied to the Primary Cardholder travelling with them.
Main Key benefits for travel.
• Annual fee: $1,450
• $450 Travel Credit every year — effectively reducing the annual fee to $1,000 when fully used.
• Unlimited eligible lounge access — including Centurion Lounges and other eligible Amex lounge networks.
• Travel insurance — complimentary cover for eligible cardmembers, subject to terms, conditions, and age limits.
• Up to 4 Additional Platinum Cards — no additional annual Card fee, which is a big advantage for a family of 4-5.
For a family of four, the $1,450 annual fee can be much easier to justify. After the $450 Travel Credit + dining credit of $400, your effective cost is $600, while you can have Additional Platinum Cards for the family and potentially get value from travel insurance, lounge access, and the other travel benefits.
That’s why, for a family or couple, the card basically pays for itself.
Still not sure which card is right for you?
Here’s a quick summary of all five options to help you find the best fit for your lifestyle and spending.
| Type | Card | Annual Fee | Key Benefit | Suitable for |
|---|---|---|---|---|
| Type 1: Everyday Essential | Coles No Annual Fee | $99 | rewards on everyday spending. | Not travelling + under $3K/month spend |
| Type 2: Travel Explorer | Bankwest More World | $270 | 10 lounge visits + no international transaction fee | Single or couple travel under three times a yearType 3 |
| : Reward Maximiser | CommBank Ultimate Awards | $0* | Strong everyday points + no international transaction fee | Not travelling + $4K+/month spend |
| Type 4: Smart Travel | Bankwest More World | $270 | Strong rewards + 10 lounge visits + no international transaction fee | Single or couple travel under three times a year + $4K+/month spend |
| Type 5: Family Travel | Amex Platinum | $1,450 | Unlimited eligible lounge access + travel insurance + $450 Travel Credit + Free Additional Cards | Couples/families who travel + $4K+/month spend |
This article is based on individual research and comparison. We are not paid to promote any of the cards mentioned, and there are no sponsored placements, advertisements or promotional deals influencing our picks.
This article is based on independent user research and comparison, not official financial advice. Offers, fees, rewards rates and eligibility requirements can change. Always check the latest official terms before applying.